Furnished rentals in Phoenix that advertise no credit check or flexible screening do exist, but most still verify you some other way, through a larger deposit, income proof, or a tenant screening report instead of a straight credit pull. Before you pay any fee, ask the provider for their exact screening policy in writing. If you want a transparent starting point, view available listings or contact us directly to confirm how we screen applicants.
TL;DR:
- A no credit check listing may still require income proof, a larger deposit, or a tenant report covering evictions, criminal records, and identity.
- Arizona landlords must disclose fees and screening categories; ask which company prepares reports and whether income proof or deposits can offset weak credit before paying.
- If a report leads to denial or worse terms, request the adverse action notice and free report within 60 days, then dispute inaccuracies with evidence.
- Providers set criteria; pay stubs, an employer contract, positive landlord references, a guarantor, or prepaid rent may strengthen applications with limited credit history.
Table of Contents
- Where to find flexible screening furnished rentals in Phoenix
- Credit score versus tenant screening report: what gets checked
- What happens after a denial: your rights and how to dispute errors
- How to qualify for a furnished rental with weak or no credit
- Why screening transparency matters more than the credit score itself
- Book a furnished rental in Phoenix without the credit check guesswork
- FAQ
- Sources
Where to find flexible screening furnished rentals in Phoenix
Furnished housing in Phoenix comes from a few distinct sources, and each tends to handle screening differently. Short-term furnished operators renting by the week or month often prioritize speed over a formal credit pull, especially for stays under 90 days. Corporate housing providers, which serve relocating employees and business travelers, frequently run a full tenant screening report because employers or relocation firms expect documented due diligence. Travel nurse housing providers, used to applicants with irregular income tied to contract assignments, often accept pay stubs or an agency contract letter in place of a conventional credit check. Private landlords advertising a single furnished unit vary the most. Some skip a credit bureau pull entirely and lean on references and a deposit, while others order the same consumer report a traditional apartment complex would use.
When searching, filter rental marketplaces for “furnished” and your intended lease length, then add terms like “no credit check,” “weekly furnished,” “monthly furnished,” or “corporate housing” to narrow results. These keywords surface listings that specifically market flexible qualification, but the phrase “no credit check” is doing a lot of work in that sentence, but it rarely means no screening at all.
A listing that says “no credit check” usually means no credit bureau pull, not no verification whatsoever. The provider may still run a tenant screening report that checks eviction history, criminal records, or identity, or they may simply require a bigger deposit and proof of income instead. Treat the phrase as a starting point for a conversation, not a guarantee.
Before you apply anywhere, ask the listing these questions directly:
- Do you run a credit pull, and if so, through which bureau?
- What company, if any, prepares your tenant screening report?
- What fees or deposit amounts apply if my credit history is thin or weak?
Credit score versus tenant screening report: what gets checked
A credit score is a single number. A tenant screening report is a broader file that many furnished rental operators pull instead of, or alongside, that score, and it can include far more than payment history. CFPB and FTC guidance explains that these reports can combine credit accounts and payment history with eviction filings, housing court records, criminal convictions, bankruptcies, identity verification, and sometimes prior rental payment history.
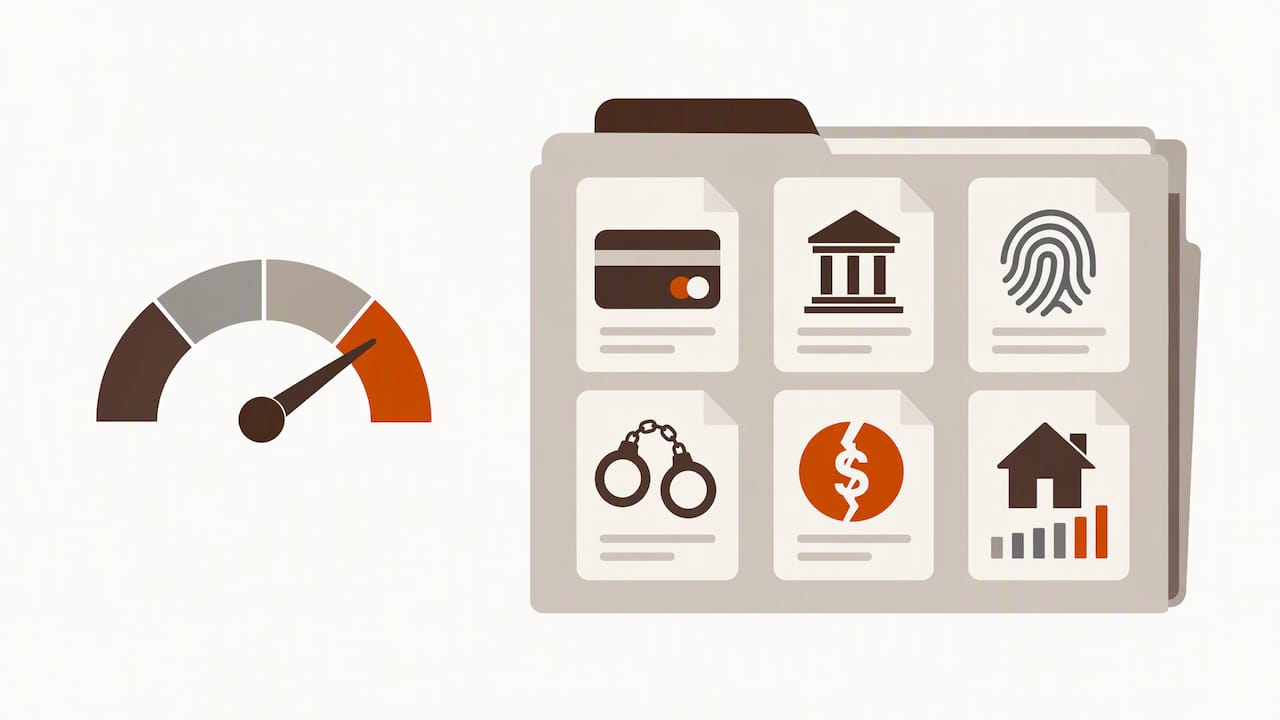
That bundling matters because a thin or damaged credit file does not automatically disqualify you if the rest of your file is clean. It also means a provider asking “what’s your credit score requirement?” may not tell you the full story: they might not pull a score at all, yet still deny you over an eviction record from years ago.
CFPB research documents that tenant background checks frequently contain errors that can block housing applicants who would otherwise qualify. That is one more reason to check your own file before a provider does.
Key data points worth knowing before you apply:
- Tenant screening reports can include credit history, eviction filings, and criminal records, not just a score.
- Landlords set their own screening criteria, since there is no universal Arizona credit requirement for furnished rentals.
- These reports count as consumer reports under the Fair Credit Reporting Act when a consumer reporting agency prepares them.
Pull your own credit reports at AnnualCreditReport.com before you apply, and ask each provider directly which report, if any, they order.
What happens after a denial: your rights and how to dispute errors
If a furnished rental provider denies your application or adds extra conditions because of a tenant screening report, FCRA and CFPB guidance requires the provider to send an adverse action notice. That notice must name the reporting company, state your right to a free copy of the report within 60 days, and explain your right to dispute inaccurate information. Ask for written confirmation of this notice if it is not provided automatically.
If a credit score played a role in the decision, the FTC notes that the provider must disclose additional details about that score, including its source, the date it was pulled, and the range it falls within.
If you are denied or offered worse terms, work through these steps in order:
- Ask the provider for the exact name of the screening or reporting company used.
- Request your free copy of that report within the 60-day window the notice specifies.
- Gather supporting documents, such as court records or proof of payment, that contradict any error.
- File a dispute directly with the screening company, and with the credit bureau if credit data is involved.
- Tell the housing provider in writing that you have an active dispute, since this can open room to negotiate.
Screening companies typically have about 30 days to investigate a dispute. If a company fails to respond or correct a verified error, you can file a complaint with the CFPB or the FTC.
Arizona law adds another layer of protection. State statute requires landlords to disclose application fee amounts and the categories of information they plan to access, and it limits certain fee practices. Request this disclosure in writing from any Arizona landlord before paying an application fee.
Pro Tip: Keep every email and screening disclosure in one folder. If a dispute drags past 30 days, that paper trail is what moves a CFPB complaint forward.
How to qualify for a furnished rental with weak or no credit
A thin credit file is not a dead end for furnished housing in Phoenix. Several tactics consistently improve approval odds when a credit pull isn’t in your favor.
A larger security deposit is the most common substitute, since it gives the provider a cushion without needing a strong credit history. A co-signer with established credit works for longer leases where the provider wants a guarantor on record. Offering to prepay rent, even one or two months upfront, signals financial stability in a way a credit score cannot. An employer letter or signed contract, especially useful for travel nurses and relocating professionals, documents steady income even when a traditional pay history is short. Positive references from a prior landlord often carry more weight than people expect, particularly for furnished and short-term operators who screen manually rather than through automated reports.
When you apply, include:
- Recent pay stubs or bank statements showing consistent income.
- A signed employer or contract letter stating your role and length of assignment.
- Contact information for at least one prior landlord willing to confirm on-time payment.
Pro Tip: Ask for the application fee amount and screening policy in writing before you pay anything. Arizona’s disclosure rules give you the right to that information upfront.
If you need housing immediately, weekly furnished operators and corporate housing providers differ mainly in speed versus cost. Weekly operators tend to move faster with lighter paperwork, while corporate housing providers often take longer but offer more consistent lease terms for stays beyond a month.
Why screening transparency matters more than the credit score itself
We built our booking process around full disclosure from the first inquiry: what we verify, what documents we ask for, and what fees apply before anyone commits to a lease. Applicants with imperfect credit are often better served by a provider who explains its process clearly than by chasing a listing that vaguely claims no screening at all. When you reach out to any furnished rental operator, ask what report they use, what income documentation they accept, and whether a deposit can offset a thin credit file. Clear answers to those three questions tell you more about your odds than any advertised policy.
— Sean
Book a furnished rental in Phoenix without the credit check guesswork
We offer fully furnished lofts across downtown Phoenix, including the Roosevelt Row Loft and Scholars Loft, built for corporate travelers, relocating professionals, travel nurses, and anyone who needs flexible lease terms without a long-term commitment. Every unit comes with a fully equipped kitchen, in-unit laundry, a dedicated workspace, and verified WiFi, so you know exactly what you’re getting before you book.
Before you commit to any furnished rental, including one of ours, ask these three questions:
- Do you run a credit pull, and through which company?
- What tenant screening company, if any, prepares your report?
- What fees or deposits apply if my credit history is thin or weak?
We answer these directly, and our lease process guide walks through exactly what to expect from application to move-in. If speed matters most, our 5-step booking process gets you into a unit fast. Browse our current properties to check availability and screening terms for the specific loft that fits your timeline.
FAQ
Can you get an apartment in Arizona with bad credit?
Yes, many Arizona landlords and furnished rental operators look beyond a credit score and weigh income, deposits, and references instead. A larger deposit, a co-signer, or an employer letter can offset a weak credit history for many providers.
Where can you rent without a credit check?
Some short-term furnished operators, corporate housing providers, and private landlords advertise flexible or no-credit-check screening, though most still verify income or require a larger deposit. Always ask directly whether the provider pulls a credit report or orders a tenant screening report instead, since the two are not the same thing.
Where can I find furnished monthly rentals in Phoenix, Arizona?
Furnished monthly rentals in Phoenix are available through short-term rental operators, corporate housing providers, and property listings like ours that offer fully equipped lofts with flexible lease lengths. Filtering marketplace searches for “furnished” plus your intended stay length narrows results to operators built for month-to-month stays.
Can a 500 credit score get an apartment?
A low credit score can still qualify for an apartment, particularly a furnished rental that weighs income, deposit size, or references more heavily than the score itself. Providers set their own criteria, so a lower score paired with strong pay stubs, a co-signer, or positive landlord references often works.
Sources
- FTC: Using consumer reports — what landlords need to know
- CFPB: Addressing inaccurate background check reports and sloppy credit-file sharing practices
- Arizona legislative text (rental application fees and disclosure provisions)
Recommended
- Phoenix Furnished Rentals Lease Process: Your Complete Application to Move-In Guide
- How to Book a Phoenix Furnished Rental in Minutes: Our Simple 5-Step Process
- Pet-Friendly Monthly Rentals in Phoenix: Navigate Deposits and Rent Like a Pro
- Charge 20–30% for Early Check In: Host Policy and Phoenix Workflow